Gold and Silver Drop as Strong Dollar Whacks Post-Fed Rebound in Stocks and Bonds
GOLD and SILVER PRICES fell on Friday afternoon in London, trimming a steep rally from Wednesday's 5-week lows as the US Dollar hit its highest since end-July and global stocks and government debt prices also retreated from their bounce following the Federal Reserve's widely expected hike to US interest rates.
While that put spot gold prices in the world's central trading and storage hub dead-flat from last week-end, the price of silver held a near-$2 gain at $66.30 per troy ounce.
Falling bond prices saw the yield on benchmark 10-year US Treasury debt rise back above 5.00% per annum, the 2-decade high reached ahead of the central bank in Washington − now under President Trump's appointee Kevin Warsh − adding 0.25 points to its overnight Fed Funds rate at 3.88%.
Despite US inflation of 3.7% on the Fed's preferred PCE measure in July, "LOWER THE INTEREST RATES...AND FAST!" tweeted Trump following Wednesday's decision, claiming that "Interest Rates in the United States should be 1%, or less, because we are the Best Credit in the World − BY FAR. Our Country is BOOMING with new Investment!"
US stocks today showed a 0.4% weekly drop on the S&P500 index while global equities traded 0.7% lower on the MSCI World Index and the Dollar price of gold at London's 3pm bullion auction made a loss from last Friday's fix of 0.8% at $4351 per troy ounce.
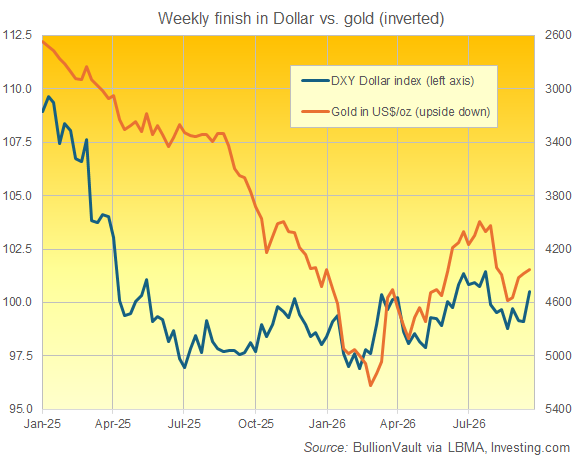
But with the US currency jumping 1.4% from last week-end on its DXY index − the sharpest weekly gain since August last year − the price of gold in Sterling and Euros both made a gain of 0.5% at today's 3pm auction, fixing around £3260 and €3796 per troy ounce respectively.
Silver had earlier traded around $67 per troy ounce at London's midday benchmarking auction, the industrially-useful precious metal's highest Friday fix so far this month.
Oil prices meanwhile flattened beneath Tuesday's 4-month closing high, showing almost no change for the week despite No.1 exporter Saudi Arabia telling refineries in Europe that they won't receive any shipments next month as supplies remain tight thanks to Iran-backed Houthi attacks on the country's east-west pipeline.
Gold in Shanghai had earlier risen to a 1-week high, fixing at ¥947 per gram at Friday afternoon's benchmarking auction for China, the No.1 mining, consumer and central-bank gold buying nation.
That cut the Shanghai gold premium relative to quotes in global trading and storage hub London from Thursday's $20 per troy ounce down to $13, but put the weekly average at almost $16.
Up from less than $4 per ounce last week, that was the highest gross incentive for new gold imports into China − where private households are increasingly choosing investment gold rather than jewellery − since mid-May, suggesting strong demand.
But gold in No.2 consumer India in contrast ran at a $60 discount to global prices this week, says Reuters, albeit better than last week's $75 discount after accounting for the government's record-high import duty and sales tax.
"The festival season is approaching, but jewellers are still not stocking much as demand remains weak," the news agency quotes a Mumbai wholesaler.
"Retail buyers are not keen to buy at current price levels," adds a jeweller in the central Indian city of Hyderabad, "and are waiting for a correction."




 Email us