Gold and Silver Rise for the Week as Tech, Crude and Copper Fall
GOLD and SILVER slipped further from 2-week and 1-week highs on Friday, trimming this week's steep rebounds from multi-month lows as US jobs data beat expectations, strengthening bets that the Federal Reserve will raise Dollar interest rates again before the end of the year, while US tech and AI stocks managed to shrug off another slump in Asian equities and reverse one-third of yesterday's plunge.
The world's largest economy added well over twice as many jobs as analysts expected in October, government data said, pushing down the unemployment rate to 4.1% as average earnings growth slowed less than forecast to 3.1% per year.
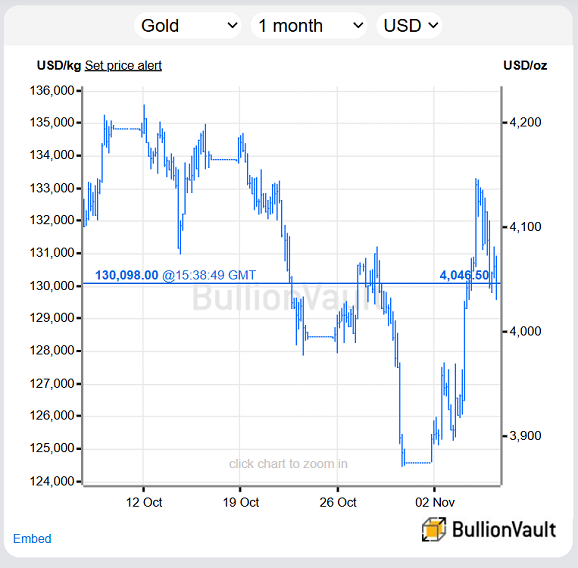
Gold cut this week's rebound off last Friday's 13-month closing low from 7.0% to 4.1% at $4050 per troy ounce, while the rebound in silver off Monday's new 2026 low shrank from 10.0% to 6.3% at $51.80.
With the Democrat Party's big win in this week's midterm elections set to challenge President Trump's AI and Iran war agendas, crude oil was on track to lose 14.0% for the week, and copper showed a 3.5% drop.
But in contrast, betting that the US central bank will raise its key interest rate again in December rallied hard on Friday's non-farm payrolls data, putting the odds that the Fed will reverse the 2nd of last year's 3 rate cuts up to nearly 77% after falling during Thursday's tech-stock crash to the weakest in 4 weeks at 67%.
The Fed will then make only 1 further rate rise in 2027, according to market positioning tracked by the CME derivatives exchange's FedWatch tool.
New York's tech-heavy Nasdaq 100 index yesterday sank 6.5%, its steepest 1-day drop in more than 18 months, to hit the lowest since mid-April.
The VIX index of price volatility in the wider US stock market meanwhile leapt by nearly 70%, making its sharpest increase since December 2024, back before US President Trump returned to the White House after winning that year's election.
"I have been trading for nearly FORTY YEARS, and my hand to God, I'm still processing what happened on Thursday," says technical analyst Tim Knight of the SlopeOfHope advisory.
"This week has seen some extraordinary moves in financial markets," says investment research publisher and 21Shares Bitcoin-Gold ETP manager Charlie Morris, noting that "with $6 trillion wiped off stockmarkets, [that] amounts to one and a half FTSE 100s.
"More weakness may follow."
But while mainstream media today attributes the tech-stock slump to US Democrat politicians threatening to curb AI data centre construction following their "blue wave" victory in Tuesday's US midterm elections, the Nasdaq 100 index has in fact been falling for 1 month today, losing 9.0% from 6 October's new all-time high prior to Thursday's historic slump.
Here in the UK, the Bank of England is querying lenders over debt extended to data center projects where no tenant is yet in place, Bloomberg reports.
The Bank yesterday raised UK interest rates to 4.0%, half-a-point above the latest pace of CPI inflation, after cutting the cost of borrowing 6 times last year.
Sterling fell on Thursday's BoE decision from 8-week highs against the Dollar and 18-month highs against the Euro, helping keep the gold price for UK investors above £3000 per troy ounce.
The price of gold in Euro terms meantime lost 2.2% from yesterday's 2-week high but held above €3600 per ounce as London trading headed into the weekend.
The yield on conventional 10-year US Treasury bonds meantime edged 2 basis points higher on Friday from yesterday's 8-week low of 4.84% per annum, while inflation-protected TIPS yields rose the same to 2.62% from Thursday's 1-week low.
That kept the gap between conventional and inflation-protected 10-year bond yields at 2.24%, implying the softest market forecast for so-called "breakeven" inflation in the US cost of living since early August, down by 1/4 of a per cent from May's 3-year high.




 Email us