Goldilocks Gets Her Porridge
No inflation, yet, as the Fed starts to raise...
SO the FOMC did the very much expected and hiked the Fed Funds Rate by 0.25% while jawboning another to come, writes Gary Tanashian in his Notes from the Rabbit Hole.
Let's leave aside that they are supposedly fighting "inflation" with a dumb monetary tool that has little to do with fighting the war and tariff-driven price increases that people are calling "inflation".
I've written til my fingers fall off that price increases are not inflation. They are the effects of the inflation the was created in Q1 2020 by the Fed (monetary) and government (fiscal). These effects manifested in 2021-2023. Birthed under Trump 1.0, made worse under Biden with Yellen channeling through Powell: "Inflation is transitory."
Trump 2.0 has brought tariffs and war. Thus, price increases. Not inflation.
Hawkish monetary policy is not the tool for that. But our dear Fed leader is not dumb. Our dear Treasury Secretary is not dumb either. What they are – in a would-be Goldilocks scenario – is two ends of the same play. The good cop buys back Treasury bonds while the bad cop hikes Fed rates.
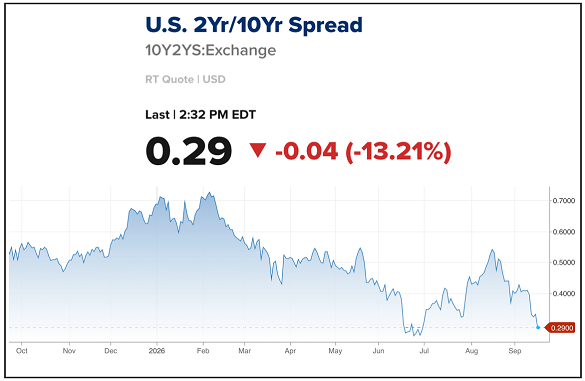
The theoretical result? Yield Curve flattening. And what does a flattening Yield Curve represent? A lovely macro painting of policy and an economy not too hot and not too cold, kind of like Goldilocks' preference for her porridge.
While the good cop stimulates on the long end, the bad cop hikes on the short end. In my opinion, they are not interested in fighting inflation. They are not stupid. They are interested in painting the macro, or having their porridge and eating it too. They are interested in flattening the Yield Curve, signaling Goldilocks. A sort of Operation Twist-lite.
As the 10-2 Yield Curve continues to flatten post-FOMC, we are in the run up to the mid-term elections. I firmly believe this was the play all along: liquefy the long end (drop yields) and firm up the short end (hike the Fed Funds Rate).
Voila! Goldilocks...for a while.
Just remember it's a near-term paint job. The longer range plan is for something completely different. And yes, it involves inflation.
But while they are painting (and if they are successful) there will be favored places to be positioned. This is a prime example of "top-down macro" guiding sector, and thus individual stock, selection.
For example, had Warsh rolled over, joining Bessent in the Market Stimulus Olympics, gold would have torn ass, likely outpaced by silver. They'd have led the "inflation trades".
But if I am correct to interpret a Goldilocks paint job, it is other areas that will outperform into early November (when Bessent's long-term bond buying spree is conveniently scheduled to end). Let's just say I am holding my gold stock short hedges (DUST & JDST) through FOMC and for now, and am not hedging my broader market positions at all. Oh, and cash is about to start paying out better income.


 Email us